
Saying Coca-Cola would outperform every single Magnificent 7 stock this year would have sounded absurd at the start of 2026. Actually, not by a little. By a lot.
KO is up roughly 33% year to date, according to Yahoo Finance. Nvidia, the supposed AI darling of the decade, is up 14.35%. Apple is up 28%. Microsoft is up 8%. Alphabet is down 10%. Meta is down 5%. Tesla is down 10%. Broadcom (AVGO), the custom chip giant that co-designs Google’s TPUs and Meta’s accelerators, is down 0.31%.
The 134-year-old company selling fizzy beverages beat them all. Jim Cramer noticed. And on Oct. 28 “Mad Money” Lightning Round, a caller asked about Broadcom.
Broadcom has been one of the greatest performers of all time, but so is Coca-Cola. I wouldn’t shoot Broadcom, and I would buy Coca-Cola.
Hold one, buy the other was Cramer’s call.
Also Read: Broadcom CEO says capital is ‘available’ after banks wavered
Broadcom remains one of the greatest wealth creators in market history
Cramer has mad respect for Broadcom. AVGO has delivered a 39.41% total return compound annual growth rate (CAGR) over the past decade, according to Investment Visual data. Yahoo Finance shows the five-year return is 603.64%. The three-year return is 321.95% as of writing.
CEO Hock Tan built that track record through a specific playbook: acquire mission-critical technology businesses, cut inefficiencies, and maximize free cash flow.
Broadcom’s AI semiconductor revenue is projected to exceed $115 billion in fiscal 2027. It’s up from an initial $100 billion outlook and scaling further toward $230 billion in fiscal 2028, fueled by heavy demand for custom AI accelerators (XPUs) and high-speed networking silicon.
More Broadcom:
- Broadcom stock gets massive $600 call even as AI fears grow
- Jim Cramer sees something Wall Street may be missing in Broadcom
- Broadcom CEO echoes Warren Buffett with warning for investors
Cramer said, “I wouldn’t shoot Broadcom,” meaning he wouldn’t sell the stock. And it’s easy to see why.
Broadcom has benefited from surging AI semiconductor revenue, strong demand for custom AI accelerators built for customers like Google and Meta, and momentum in next-generation networking hardware.
Those strengths helped push the stock to an all-time high of $495 in June 2026, as noted by TheStreet. But Broadcom has since given back its year-to-date gains.
To me, that shows what can happen when investors price in years of strong growth ahead of time. Even an exceptional business can struggle to meet expectations that high.
What Coca-Cola just reported, and why it surprised everyone
The main reason Cramer is turning his attention to Coca-Cola (KO) is its better-than-expected earnings report, released just a day before his Lightning Round appearance.
Coca-Cola reported Q3 fiscal 2026 revenue of $13.4 billion, up 7% year over year (YoY), beating consensus estimates of $12.9 billion. Non-GAAP comparable EPS came in at $0.91, up 11% YoY, beating estimates of $0.88. Global unit case volume grew 5%, with particularly strong performance in Latin America, India, China, and Brazil.
CEO Henrique Braun issued a confident statement: “By staying close to consumers and executing with agility across our global system, we are delivering quality growth while continuing to invest in the capabilities, brands and people that will fuel our future.”
Related: Pepsi vs. Coca-Cola: Which Dividend King stock will outperform in 2027?
Management also raised full-year 2026 guidance. Comparable EPS growth is now expected to increase by at least 11%, up from prior guidance of 9%-10%. Organic revenue growth is expected to climb at least 5%. Free cash flow is projected at at least $13 billion, according to the Q3 fiscal 2026 statement.
For context, Coca-Cola has typically delivered low-single-digit sales growth, and mid-to-high-single-digit earnings growth in recent years.
Guidance calling for at least 11% earnings growth is a meaningful step up that reflects two specific tailwinds: the company’s FIFA World Cup sponsorship driving volume growth, and a weak U.S. dollar boosting results from international operations.
 Coca-Cola reported Q3 fiscal 2026 revenue of $13.4 billion, up 7% year over year, beating consensus estimates of $12.9 billion.
My take: Cramer is right on direction, but timing matters
I want to be honest about something here, because the chart is telling me something worth noting alongside Cramer’s call.
Coca-Cola now trades at 26 times forward earnings, according to Yahoo Finance. For most of the past decade, KO has traded in the low 20s. The premium is largely explained by the acceleration in growth and the World Cup market, as mentioned in the Q2 report.
If either of those factors fades heading into 2027, the stock could de-rate toward its historical multiple, and that’s a meaningful downside risk.
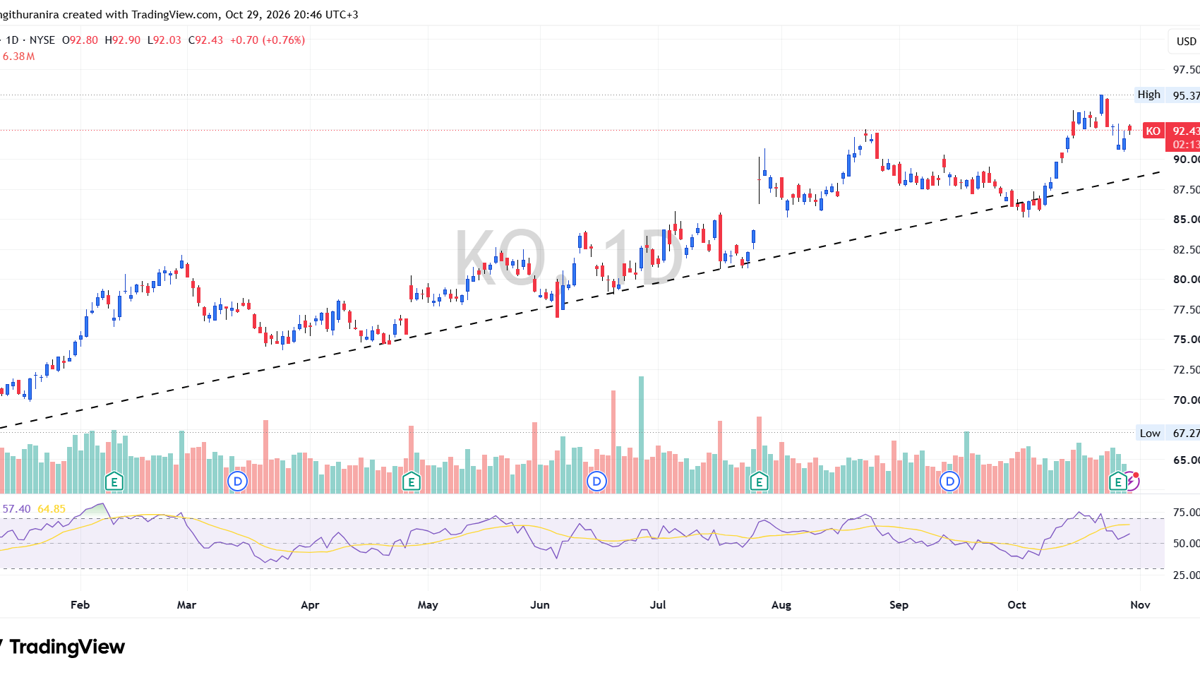
Technically on the daily chart, KO has respected an ascending trendline since January 2026, with six tests and six rejections, each followed by a bullish trend.
That technical support around $88 remains intact. But the current forward yield of approximately 2.29%, according to Macrotrends data, is below the 3% level that has historically represented the best entry zone for long-term dividend investors.
Cramer says buy Coca-Cola. My view is that I’d prefer to see the stock pull back toward its ascending trendline, where the dividend yield could approach 3%. That’s where I think the long-term investment case becomes more attractive, regardless of short-term price momentum.
As for Broadcom, I think the decision is much simpler. With AI revenue projected to reach $115 billion in fiscal 2027 and a decade-long track record of 39% annualized total returns, I wouldn’t give up on the stock just because it has surrendered its year-to-date gains.
For me, this looks more like a test of patience than a reason to walk away.
