Few Wall Street voices command the same respect as billionaire David Tepper.
As the founder and president of legendary hedge fund Appaloosa Management, Tepper built a $28.5 billion personal net worth, purchasing the NFL’s Carolina Panthers and Major League Soccer’s Charlotte FC, through fearless, prescient macro calls when everyday investors were paralyzed by fear.
From buying distressed bank stocks at the bottom of the 2009 financial crisis to igniting the famous 2010 “Tepper Rally” and calling China’s stimulus rebound, he has spent more than three decades turning market panic into generational wealth.
Today, Appaloosa operates mainly as a family office overseeing $17 billion in total assets under management, according to Forbes, including a closely watched $7.56 billion U.S. equity portfolio.
As Q3 Form 13F filings roll in across a jittery tech market, Tepper just showed off a brand-new $172 million stake in a polarizing mega-cap tech giant caught at the center of Wall Street’s fiercest AI debt debate.
Why Tepper’s $172 million Oracle bet defies Wall Street’s AI debt fears
According to Appaloosa Management’s Q3 13F filing, the firm initiated a brand-new position of 1,253,932 shares in Oracle Corp. (ORCL), valued at $172.16 million as of Sept. 30.
On the surface, scooping up shares in Oracle at this point looks remarkably counterintuitive. Bears, including “The Big Short” investor Michael Burry, have sounded the alarm on Oracle over its aggressive, debt-fueled AI data center buildout.
More Wall Street:
- Arista Networks stock gets fresh backing from Jim Cramer and Wall Street
- Oracle stock sinks as Wall Street confronts a $20 billion AI problem
- Wall Street just got a candid look at who is winning the AI race
In its most recent quarterly showing in fiscal Q1 2027, Oracle’s CapEx hit $28.5 billion, eclipsing $23.1 billion in operating cash flow and pushing free cash flow to negative $5.4 billion, with positive free cash flow not expected to return until late fiscal 2028.
In addition, total debt is near $125 billion, interest expenses have surged 55%, and credit jitters recently hit a fever pitch after HSBC sold a $300 million Oracle-linked New Mexico data center construction loan at 85 cents on the dollar, according to Bloomberg.
Nevertheless, Tepper has built his empire analyzing stressed balance sheets.
Tepper famously explained his contrarian philosophy in this way: “We have this saying: The worst things get, the better they get.”
“I am the animal at the head of the pack. I either get eaten, or I get the good grass,” he also said.
Perhaps the bull case Tepper might be backing is linked to pre-booked demand and a discounted valuation. Oracle’s cloud infrastructure sales recently skyrocketed 121%, while its remaining performance obligations (RPO) (contracted backlog) swelled to an astonishing $664 billion, roughly half of which converts to sales within 36 months.
Because debt fears have compressed Oracle’s forward price-to-earnings multiple to just 14.7 times versus the industry’s 21 times average, Tepper is getting hyperscale AI growth at a value multiple, Seeking Alpha noted.
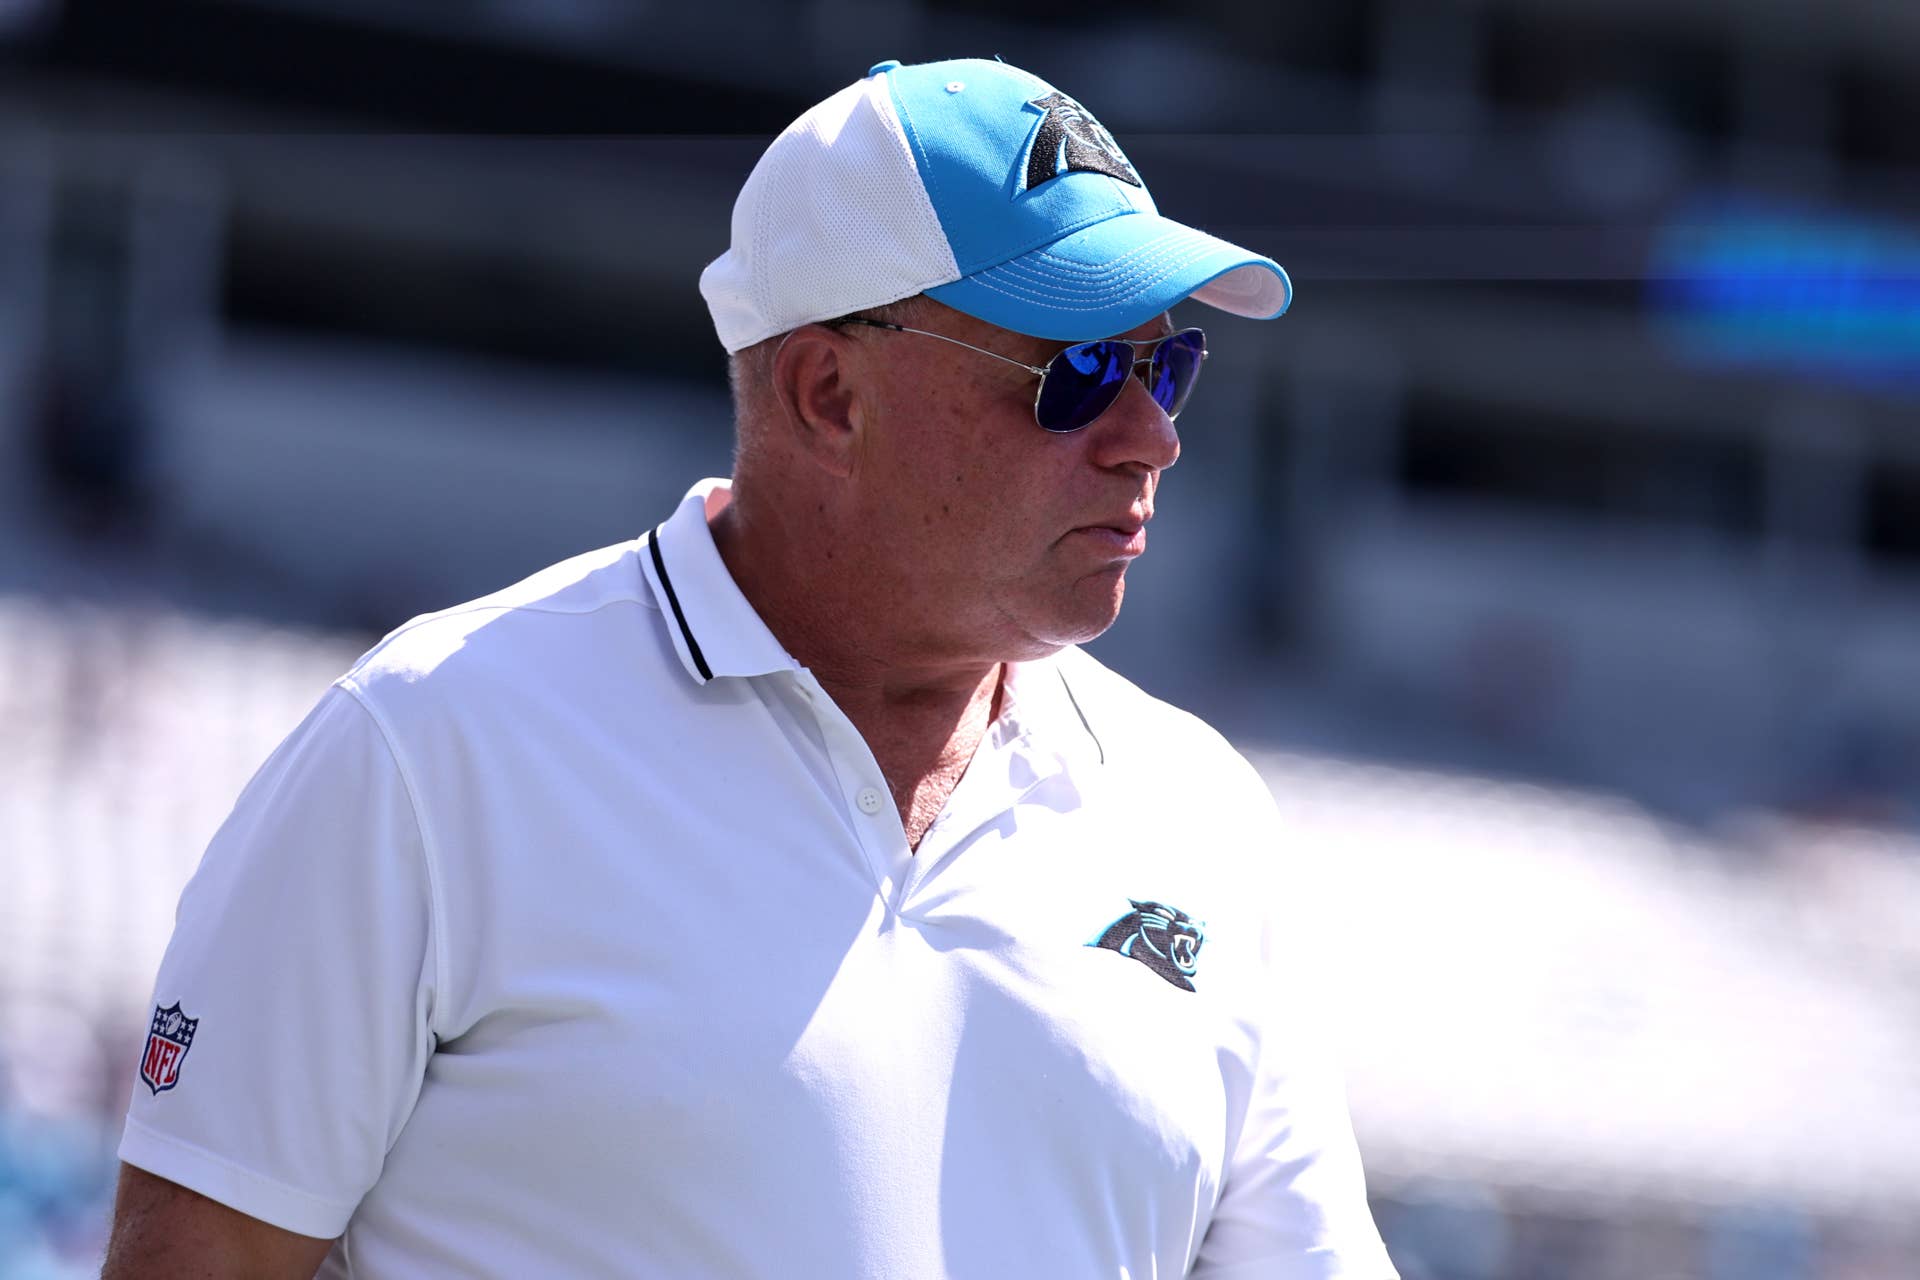 Appaloosa disclosed a new $172 million Oracle stake in its Q3 filing.
How Tepper rotated out of Big Tech ad giants and into SpaceX and chipmakers
Oracle wasn’t Tepper’s only high-conviction move in Q3.
Across Appaloosa’s portfolio, Tepper’s firm has rotated aggressively out of consumer-facing internet and advertising platforms and into physical AI hardware, memory chips, and orbital infrastructure.
Most notably, Tepper raised his stake in Micron Technology Inc. (MU) by 28%, adding 275,000 shares to reach 1.25 million shares, valued at $1.33 billion, surpassing Amazon (AMZN) as Appaloosa’s number-one holding.
He also bumped his position in Elon Musk’s SpaceX (SPCX) by a staggering 1,626%, adding 3.66 million shares to bring his stake to 3.88 million shares worth $556.55 million.
At the same time, Tepper leaned into chip manufacturing and data-center hardware. He raised his Nvidia (NVDA) stake by 31% (adding 475,000 shares to reach 2 million shares worth $456.76 million), while boosting chip-equipment maker Lam Research (LRCX) by 63% to $205.32 million. Tepper also opened new stakes in Applied Materials (AMAT, 225,000 shares worth $115.06 million).
To fund that hardware blitz potentially, Tepper’s firm cut Alphabet (GOOG) by 46% (-850,000 shares to $340.74 million), cut Meta Platforms Inc. (META) by 22% (-150,000 shares to $380.72 million), and trimmed Amazon by 10% (-525,000 shares to $1.11 billion).
It also pared NRG Energy Inc. (NRG) by 19% and Baidu Inc. (BIDU) by 15%.
What Tepper’s Q3 buy means for Oracle stock investors now
For everyday investors weighing whether to buy Oracle stock amid the ongoing AI capex debate, Tepper’s $172.16 million entry carries a ton of weight.
What’s especially pertinent to Oracle’s case is that Tepper began his career on Wall Street, dissecting corporate debt covenants, high-yield bonds, and credit risk. His firm’s willingness to commit more than $172 million to Oracle could be interpreted to mean that the market’s solvency and cash-burn fears are overblown.
Also, pairing Oracle with massive additions in Micron, Nvidia, Applied Materials, and Lam Research shows Tepper believes the AI data-center buildout is far from finished.
That said, Oracle shareholders need to stomach negative free cash flow and periodic credit-market noise over the next 18 months, and then weigh out the development accordingly.
Related: Morgan Stanley resets S&P 500 target for 2027 as tech stocks slide
