On Oct. 14, 2016, Broadcom shares traded at $17.01. So, a $10,000 investment in the tech stock would have let you purchase $588 shares.
Back then, the chip giant paid shareholders an annual dividend of $0.20 per share. So, you would have earned $117.6 million in annual dividends, for a yield of just 1.17%.
Ten years later, that stake is worth $273,588.57 if we adjust for dividend reinvestments. Notably, with every cent of dividend reinvested, you would own 766 shares today.
In October 2026, the company pays shareholders an annual dividend of $2.60 per share, which translates to $1991 in annual dividends. So, the yield-on-cost has increased to almost 20% over the last 10 years.
The Broadcom (AVGO) stock price has risen 2,637% cumulatively, or at a compound annual growth rate of 39.21%.
Also Read: Broadcom CEO echoes Warren Buffett with warning for investors
Over this period, the $10,000 position held about 30% more shares than the original purchase due to dividend reinvestments.
If we do not reinvest dividends, the yield-at-cost falls to 14.9%, given the annual dividend will be around $1,493.
Broadcom dividend key ratios
Payout ratios below are calculated from figures Broadcom reported for the third quarter.
- Quarterly dividend: $0.65 per share
- Annual dividend: $2.60 per share
- Dividend yield in 2026: 0.73%
- 10-year yield on cost: 19.4% with reinvestment, 14.9% without
- Annual dividend expense: $12.4 billion
- Estimated FCF in fiscal 2026: $49 billion
- Dividend payout ratio: around 25%
Broadcom is generating enough cash to continue its dividend hikes.
Given consensus estimates compiled from TIKR, analysts tracking the tech stock project free cash flow to grow from $26.91 billion in fiscal 2025 (ended in October) to $$49 billion in 2026 and $197 billion in 2030.
At a 25% payout ratio, the company’s annual dividend could surpass $10 per share by 2030.
It means the yield-on-cost could eventually surpass 80% even without a dividend reinvestment plan.
The cash behind Broadcom’s payout
Valued at a market cap of $1.70 trillion, Broadcom is among the world’s largest semiconductor companies.
Despite its massive size, Broadcom continues to grow at an enviable pace.
In fiscal Q3, it reported record revenue of $29.6 billion, up 86% year over year. Artificial intelligence chip sales more than tripled to $16.7 billion.
Its operating margin stood at 68%, while free cash flow surged to a record $13.7 billion.
The company paid $3.1 billion in dividends during the quarter, less than a quarter of its free cash flow.
What Hock Tan says about Broadcom’s cash
The key question for investors is what comes next.
At the Goldman Sachs Communacopia + Technology Conference on Sept. 8, Broadcom CEO Hock Tan said Broadcom will end October with a record amount of cash, stating:
“So we’re going to generate a lot of cash.”
The board could raise the dividend or buy back stock using this cash pile.
Paying down debt makes less sense to Tan because the company took on the debt when interest rates were much lower. CFO Amie Thuener put the weighted average coupon at 4%.
How much of FCF would go to dividends is “still a long way off,” Tan said without committing to anything.
“Well, give me three months,” he told the audience.
The board usually settles capital allocation at its December meeting, and Broadcom reports fourth quarter results on Dec. 9.
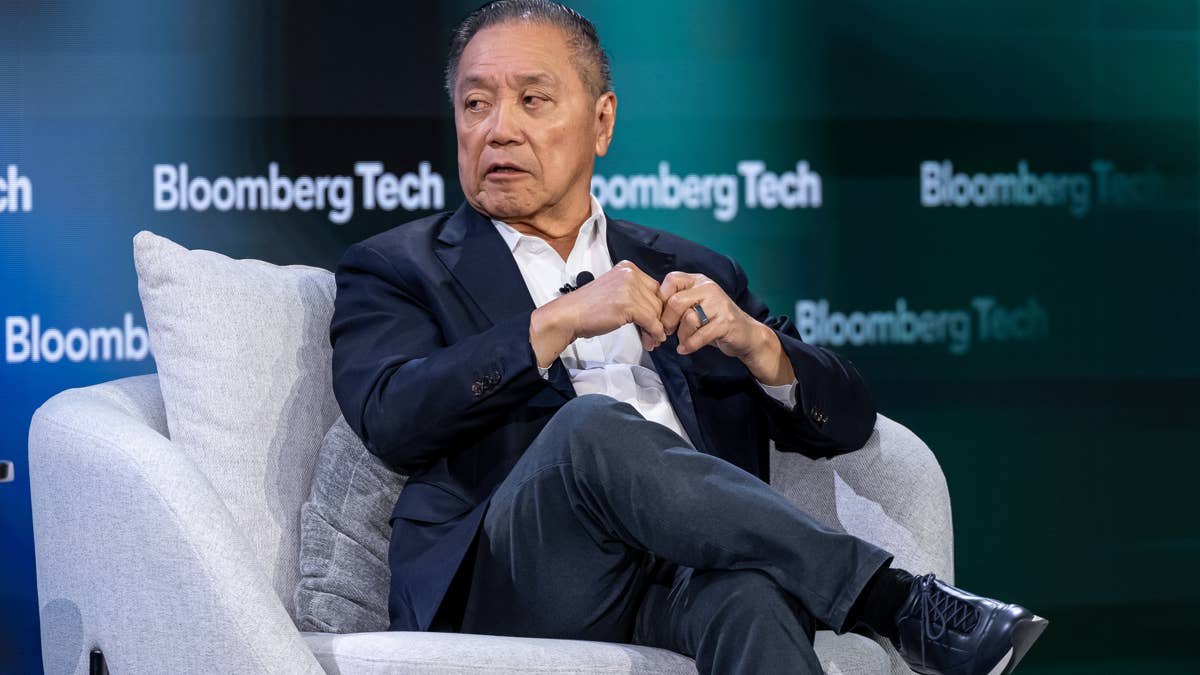 Hock Tan, the CEO of Broadcom, is bullish on AI demand.
Is Broadcom stock still a good buy?
Investing in quality dividend stocks allows you to generate a recurring income stream and long-term capital gains.
Moreover, the best dividend stocks like Broadcom consistently increase dividends each year.
“Going back to 1960, 85% of the cumulative total return of the S&P 500 Index can be attributed to reinvested dividends and the power of compounding,” according to a Hartford Funds report,
More Dividend Stocks:
- 2 dividend stocks that pay you more than the 10-year Treasury note
- Jim Cramer issues blunt warning on high-dividend stocks
- How much to invest in Ford stock to earn $500 in annual dividends
So, let’s see if AVGO stock is still a good buy.
If Broadcom trades at 20x forward FCF, below its current 22.5x multiple, it could more than double in the next three years.
Of the 29 analysts covering Broadcom stock, 27 recommend “Buy,” and two recommend “Hold.” The average Broadcom price target is $519, suggesting 45% upside from current levels.
However, the yield-on-cost shows how Broadcom has performed in the past decade. The tech giant will not be able to replicate that performance going forward.
Broadcom also relies on six custom-chip customers, indicating heavy customer-concentration risk.
Basically, Broadcom remains a top buy for investors who remain bullish on the AI trade.
