Every money plan you make rests on one number you don’t control: the cost of borrowing.
It sets what you pay for a house, a car and the balance you carry on a credit card. It also decides what your savings account, CD or bond fund pays you back.
For most of 2026, that number has climbed. The 10-year Treasury yield reached 5.34% on Sept. 30, its highest level since 2002 and more than one percentage point above where it sat Feb. 27, according to Federal Reserve data cited by the Senate Banking Committee’s Democratic staff. It still closed at 5.24% on Oct. 9.
Mortgage rates followed the bond market up. Freddie Mac’s 30-year fixed average hit 7.40% for the week of Oct. 8, its highest reading in a year, according to data compiled by Mortgage News Daily.
So when the country’s top money official and one of his loudest critics trade letters over who is to blame, you have real dollars riding on the outcome.
On Oct. 10, Treasury Secretary Scott Bessent posted a two-page letter to Sen. Elizabeth Warren (D-Mass.), dated Oct. 9, on X, answering her demand for a plan to bring rates down. It opens with an insult and closes with a handwritten holiday greeting.
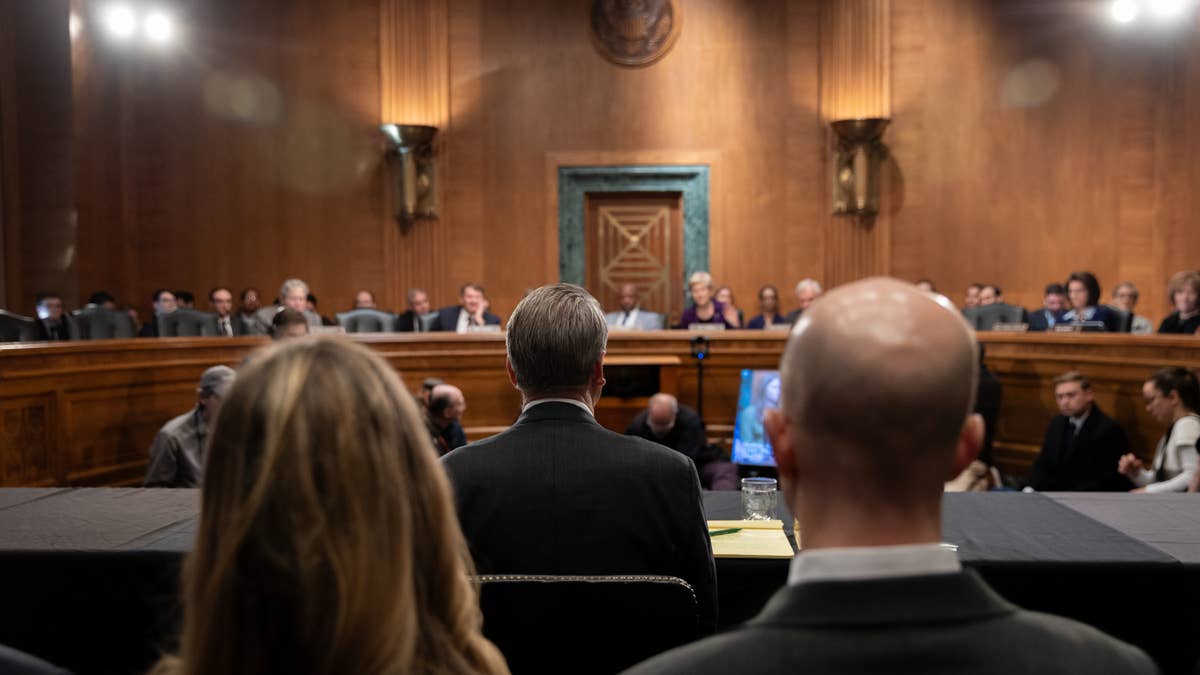 Treasury Secretary Scott Bessent defended his bond buybacks in a letter to Sen. Elizabeth Warren.
Warren’s $361 mortgage math and buyback complaint
Warren’s Oct. 7 letter, sent as ranking member of the Senate Banking Committee, ties rising yields directly to household budgets. She argues that higher Treasury yields push up what you pay on mortgages, car loans and credit cards.
Her office ran the math on a typical home. Using the National Association of Realtors’ $429,100 median price and a 20% down payment, staff compared the 30-year rate of 5.99% on Feb. 27 with 7.57% on Oct. 2, as tracked by Mortgage News Daily.
That gap works out to about $361 more each month, the Senate Banking Committee letter states. I re-ran the figures on a $343,280 loan and got the same answer: about $2,056 a month at the February rate versus $2,417 now.
Related: Zillow reports surprising housing market shift
Warren also took aim at Bessent’s bond buybacks, the program that swaps short-term Treasury bills for longer-dated bonds. Treasury announced on Aug. 19 that it would double the size of those operations, and three rounds followed:
- $5.2 billion on Sept. 10
- $4.1 billion on Sept. 24
- $6 billion on Oct. 1
“Unfortunately, your intervention is failing,” Warren wrote, noting that yields rose after the first two rounds. She asked five questions, including whether Treasury will draw down its cash account to fund bigger buybacks, and set an Oct. 21 deadline for answers.
Bessent’s reply mocks Warren and blames Biden-era spending
Bessent did not wait for the deadline. He opened by telling Warren her letter “adds to the mounting body of evidence of your complete paucity of knowledge about financial markets.”
More Housing Markets:
- Americans are souring on the economy as housing gets harder again
- Mortgage rates just surpassed 7%. Here’s why they’re rising
- Jeff Bezos has a blunt answer for why housing is so expensive
On the buybacks, he rejected Warren’s framing outright. The “interventions” she called unprecedented, he wrote, “have been underway since May 2024,” which places the program’s start under his predecessor, Janet Yellen.
He then made his case for the program and for the administration’s tax law. Here is what Bessent claimed in the letter:
- The buyback program reduces market volatility, increases the convenience yield of Treasury securities and “ensures the best value for the taxpayer.”
- The average tax refund this filing season was over $3,400, an increase of 11% from the previous year.
- More than 30 million workers claimed No Tax on Overtime, and more than seven million claimed No Tax on Tips.
- More than 37 million seniors claimed their enhanced deduction, and more than 34 million families claimed the enhanced Child Tax Credit.
Bessent also accused Warren of cheering the Biden administration’s spending while inflation hit a 40-year high. He wrote that her view of the economy “depends on who occupies the White House.”
The last page turns personal. Bessent defended Treasury staff after Warren questioned their staffing in a recent interview, citing an Oct. 7 Punchbowl News piece in a footnote.
He then renewed an offer, first made in an Aug. 28 post on X during a spat over Treasury’s yen intervention, to give Warren a “Foreign Exchange for Dummies” tutorial. If she passes, he wrote, he would add a “Fixed Income for Dummies.”
Below his signature, in green ink, Bessent wished Warren a happy Indigenous Peoples’ Day in advance of the Oct. 12 holiday. The note appears to reference the long-running controversy over Warren’s past claims of Native American ancestry.
The housing cost Treasury’s letter never disputes
Here is what I find most telling for your wallet. Bessent never disputes Warren’s 7.57% mortgage rate or her $361 monthly figure.
His defense of buybacks rests on liquidity, the ease of buying and selling Treasuries. That matches Treasury’s official description of the program, but Bessent has also said publicly that long-term rates are too high.
Mortgage News Daily noted that he told reporters there was a “signaling component” to the expanded buybacks. The market has tested that signal and pushed back.
After the first expanded operation on Sept. 10, Treasury bought less long-dated debt than traders expected, and the 10-year yield climbed to 4.95%, Bloomberg reported via American Banker. Yields kept rising into the end of September.
A $323 refund bump against a $4,330 yearly bill
Both officials are quoting real numbers. They just describe different parts of your budget.
The IRS filing season statistics through April 24, a week after the filing deadline, show an average refund of $3,268. That is up 11% from $2,945 a year earlier, a gain of about $323.
Bessent’s 11% checks out. His “over $3,400” matches IRS readings from earlier in the season, such as the $3,462 average through April 3, before later, smaller refunds pulled the average down.
Now put that next to Warren’s mortgage figure. A new buyer paying $361 more a month spends roughly $4,330 extra per year, and close to $130,000 more in interest over the life of a 30-year loan.
In other words, the average refund increase would cover less than one month of the higher payment. That comparison has limits, and you should know them before drawing conclusions:
- If you already own a home with a fixed-rate mortgage, rising rates do not change your payment.
- A bigger refund can reflect how much was withheld from your paychecks, so it is not the same as your full tax savings.
- The overtime and tips deductions help specific workers far more than the average filer.
There is an upside, too. The same yields that hurt borrowers mean savers can earn more on Treasury bills, CDs and money market funds than they could a few years ago.
Steps borrowers and savers can take before Oct. 21
You can’t set the 10-year yield, but you can control how exposed you are to it. A few steps are worth weighing now.
If you are shopping for a home, get quotes from several lenders on the same day and ask about rate locks. Even a small rate difference adds up to thousands of dollars over a 30-year loan.
If you carry a credit card balance, paying it down beats almost any return you can earn elsewhere while rates stay high. If you have cash on the sidelines, compare what short-term Treasuries and high-yield savings accounts pay before leaving it in a checking account.
The next dates to watch are Warren’s Oct. 21 deadline and the Federal Reserve’s Oct. 27-28 policy meeting. The bond market’s reaction to both will matter more for your next mortgage quote than either letter.
Letters make headlines. Your next loan quote is the number that lands in your budget, so shop it hard.
Related: Bessent is betting a construction boom brings factories home
