Lululemon is facing another setback as it struggles to draw customers into its stores, a challenge it has been battling in recent months.
The athletic apparel retailer saw its comparable sales in North America decrease by 12% year over year in the second quarter of 2026, while its net revenue in the region dropped by 8%, according to its latest earnings report.
On an earnings call on Sept. 9, Lululemon Chief Financial Officer Meghan Frank said the company’s sales were negatively impacted by several headwinds, including a shift in customer demand from tighter athletic wear to looser fits, which contributed to a 20% decline in leggings sales.
“As we moved into Q2, we faced negative commentary in the media and social channels, which impacted traffic, and softer-than-planned response to some new product launches, which contributed to a moderating sales trend,” said Frank.
Lululemon gets a new negative stock rating
Amid these challenges, Lululemon’s stock received an underperform rating from BMO Capital Markets, citing the retailer’s poor second-quarter performance.
In an analyst note, BMO Capital Markets analyst Kelly Crago gave Lululemon stock a sell rating and a $70 price target as the firm expects an additional 28% decrease from the stock’s closing price on Sept. 10, according to a recent TipRanks report.
Crago said in the note that Lululemon’s “irrelevance with the consumer is showing up in the numbers.”
She also said that the company’s second-quarter earnings reveal it is losing market share across the Americas and China to smaller athletic-wear competitors like Alo Yoga and Vuori, which are increasingly resonating with consumers.
Related: Kohl’s expands in-store partnership as customers look elsewhere
For instance, while Lululemon’s market share dipped 10 percentage points to 43.9% in August, shares of Alo Yoga and Vuori rose 5.9 percentage points and 2.2 percentage points, respectively, according to a recent Reuters report citing data from M Science.
“The product engine that has fueled this company for years is very stale because it’s a much tougher category where athleisure is out of favor,” said Crago.
BMO Capital Markets’ underperform rating on Lululemon stock comes after BofA Global Research lowered its price objective on Lululemon (its estimate of where the stock could trade) from $140 to $122, according to a Sept. 4 research note obtained by TheStreet.
The firm maintained its neutral rating on the stock but cut its earnings-per-share forecast by 13% for fiscal year 2026 and by 31% for fiscal year 2027.
In the research note, BofA Global Research analyst Lorraine Hutchinson said that Lululemon’s weak second-quarter performance “push” the company’s “recovery timeline further out.”
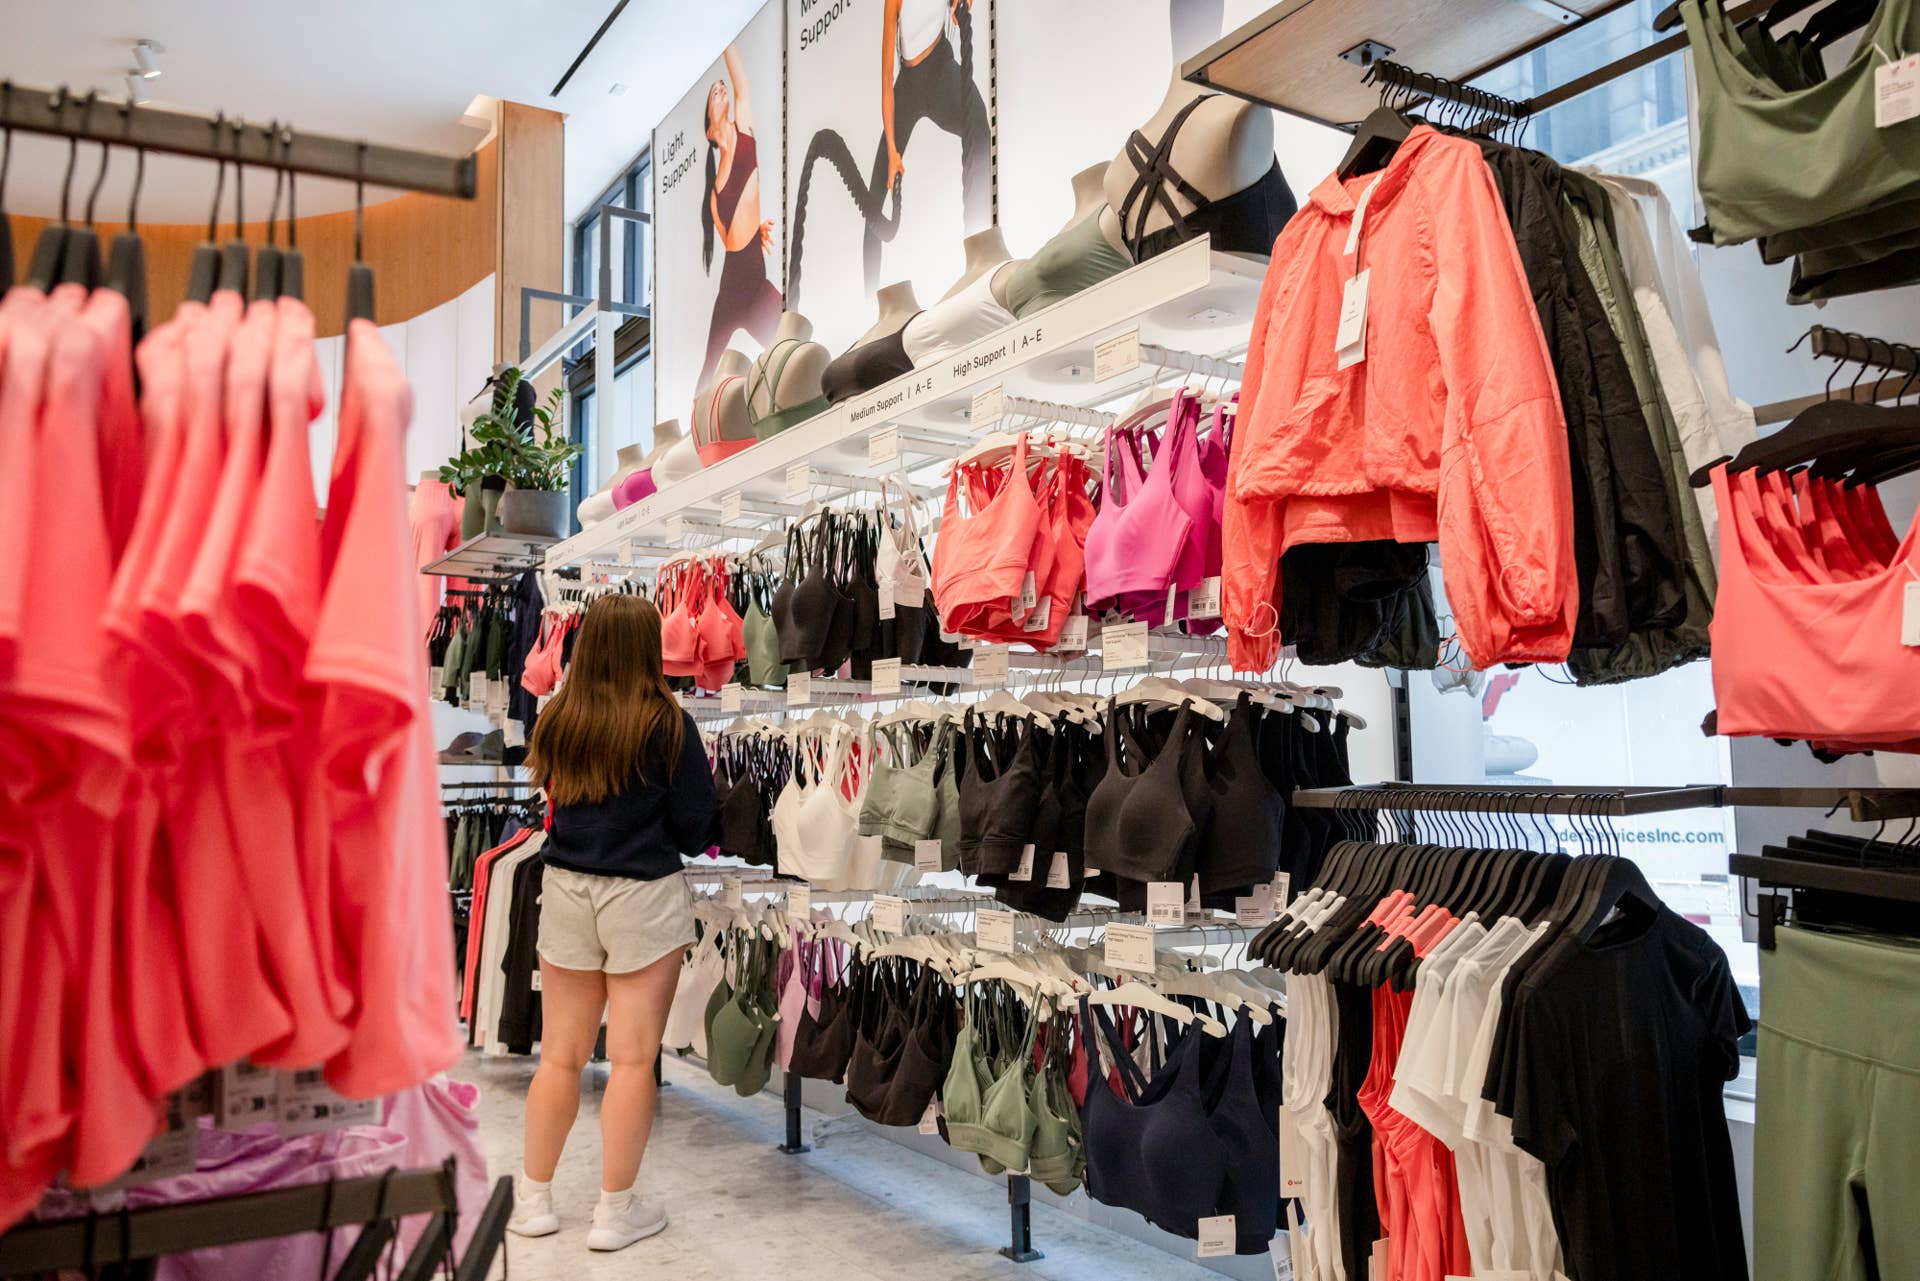 Lululemon receives an underperform stock rating from BMO Capital Markets.
Lululemon faces a more cautious consumer
Wall Street’s response to Lululemon’s second-quarter earnings comes during a time when foot traffic in the retailer’s stores has worsened in recent months.
According to recent Placer.ai data sent to TheStreet, Lululemon’s same-store visits declined by 1.9% year over year in June. In July, visits dipped by 1.9% again, and dropped by 6% in August.
“Lululemon’s performance aligns with obstacles that many brands currently face: more discerning discretionary shoppers and the squeezing of aspirational consumers,” said Elizabeth Lafontaine, a retail analyst and director of research at Placer.ai, in a statement to TheStreet.
“The increased competition in the luxury athleisure market has also added pressure to stand out and maintain excitement with shoppers,” she continued.
U.S. consumers are indeed restricting their discretionary retail spending. A survey from A&M Consumer and Retail Group in April revealed that roughly 30% of consumers expect to spend less on clothing and footwear this year by cutting volume, taking advantage of sales and promotions and making fewer impulse purchases amid economic pressures.
Lululemon maps a plan to win customers back
As consumers rethink their spending, Lululemon is doubling down on its turnaround efforts by focusing on offering more innovation.
This includes introducing more loose-fitting styles in its stores after items, such as its Groove Wide-Leg, Align Foldover Jogger, Breezily and updated Dance Studio Pants, performed well during the second quarter.
It is also adding new cold-weather outerwear styles, featuring its Wunder Puff and Featherweight Down franchise, and a new version of its popular Big Cozy.
More Retail:
- Ross Stores customers will soon feel a notable change in stores
- Publix struggles to reverse concerning customer behavior
- Kohl’s drops generous offers as it tries to win back customers
“The markets we operate in are competitive, which makes it imperative for us to focus on unique and innovative ways to inspire our guests,” said Frank during the company’s Sept. 9 earnings call.
Lululemon will also continue to shrink its offerings by reducing SKUs (stock-keeping units) in its stores, a move it believes will make the customer experience more premium.
Additionally, it will enhance its store and digital experience, and increase and redirect its marketing spend.
While Frank said Lululemon will “continue to focus on improving full price selling” to attract customers, it will also increase its markdowns by approximately 60 basis points in the third quarter of this year compared to the same quarter last year.
Lululemon’s turnaround strategy could shift as Heidi O’Neill became the company’s new CEO on Sept. 8, replacing Calvin McDonald, who stepped down from the role on Jan. 31. Frank said O’Neill will “define the path forward for Lululemon’s next chapter” as she evaluates the company’s “strategy and current action plans.”
As Lululemon changes course, it expects its U.S. revenue to be down in the low double digits for the full year of 2026, compared to 2025.
Related: Ross Stores customers will soon feel a notable change in stores