A pricey S&P 500 (especially when set against a backdrop of inflation, high energy prices, and geopolitical uncertainty) can make the stock market look like a poor place to park new money.
Josh Wein, portfolio manager of the Hennessy Cornerstone Growth Fund at Hennessy Funds, sees a more nuanced picture. He says the index’s roughly 21-times-earnings valuation is heavily shaped by its largest companies, while many S&P 500 stocks, especially mid-caps, are actually trading at lower multiples.
For investors who already own broad index funds, his practical point is to check whether market-cap weighting has left their portfolios overly dependent on a handful of mega-cap winners, then consider whether mid-caps can add diversification in an increasingly uncertain market.
Who is Josh Wein & why should we listen to him?
Wein recently sat down with TheStreet’s Caroline Woods to discuss the S&P’s hidden gems amid an uncertain market. He currently works at Hennessey Funds, a firm that designs and manages both mutual funds and ETFs, with a total of $4.1 billion in assets under management.
Prior to becoming a fund manager at Hennessey, Wein was the Director of Alternative Investments and co-portfolio manager at Sterling Capital Management and served as a portfolio manager at Bellator Capital Partners. He also worked as an associate equity research analyst at First Union Securities.
At Hennessy, Wein manages or co-manages a total of 10 different funds, including the company’s Cornerstone Mid Cap 30 Fund, a concentrated, actively managed portfolio comprising just 30 companies, hand-selected from the mid-cap market for their momentum, earnings growth, and fundamentals.
These are the types of stocks he highlights as potential opportunities buried in the S&P 500 in today’s market.
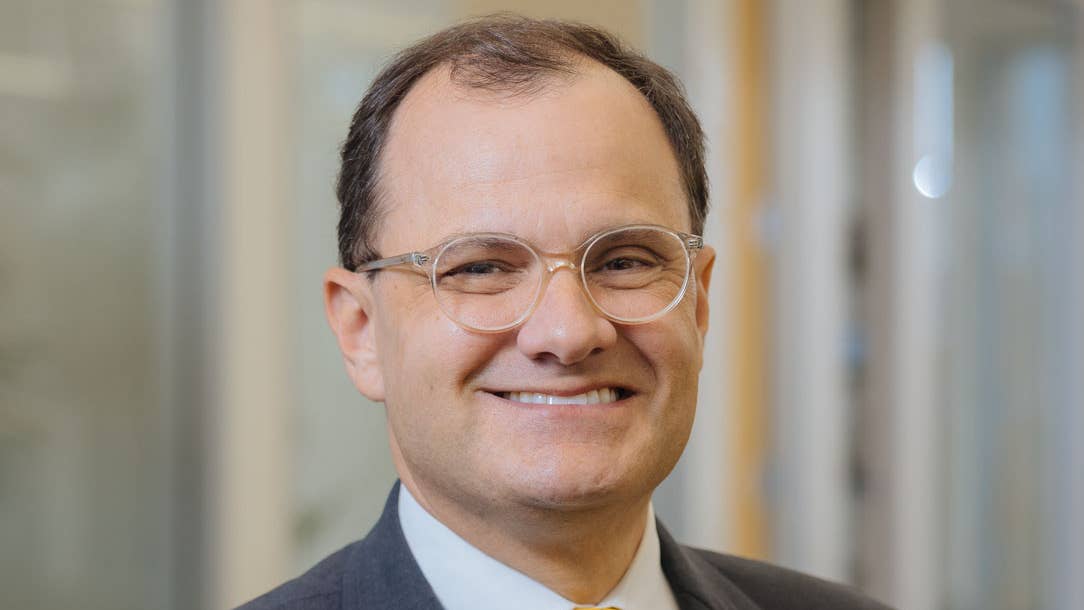 Josh Wien manages a number of funds at Hennessy, including a mid-cap-themed fund with just 30 holdings.
Why consider mid-caps in today’s uncertain market?
As we edge closer to the fourth quarter after witnessing the first Federal funds rate increase since 2023, calls for an impending pullback, bear market, or even market crash have increased in both frequency and urgency. On Sep. 18, for instance, The Motley Fool’s Dana George wrote a piece titled, “A Bear Market Is Coming — We Just Don’t Know When.”
No one knows when exactly it will happen, but most agree we’re overdue for some kind of correction. On average, there are 3.5 years or so between bear markets, and we’re already 4 years past our last. And when equities do fall, most think the mega-cap tech giants deeply tied to the AI spending and buildout frenzy will fall the hardest.
This does not make mid-caps a universal replacement for an S&P 500 fund, and it does not make every cheaper stock attractive. Wein’s own rules-based process looks for three things together: a reasonable valuation, improving earnings, and stock-price momentum, meaning the share price has begun to rise.
Here is how he applies that framework to an earnings-driven market, artificial intelligence infrastructure, and the risks that could disrupt the case.
Why the S&P 500 can look expensive while many stocks do not
The apparent contradiction starts with how the S&P 500 is built. It is a market-cap-weighted index, so companies with the largest total stock-market values receive the largest weights. When a small group of giant companies commands high valuations, their influence can raise the valuation of the entire index even if many other stocks trade more modestly.
Wein said the S&P 500 was trading at about 21 times earnings in the interview, while the average stock in the index traded at about 17 times earnings. He put mid-caps, companies smaller than the market’s biggest firms (but larger than its smallest), at roughly 16 to 16.5 times earnings.
Certainly, the S&P 500 trading at about 21 times earnings, and it’s a market-cap-weighted index, and the market is definitely paying for the liquidity that comes with these big names like Nvidia and Microsoft. But the average S&P stock is at about 17 times earnings.
Wein’s distinction matters because “the market” is often used as shorthand for the index level. An investor deciding whether to add money is making a different decision: whether the particular stocks, fund, or index exposure being purchased offers an acceptable price for the earnings and risks involved. A broad index can remain a useful core holding while still carrying more exposure to its largest constituents than its owner realizes.
Why S&P 500 indexing can become a momentum bet
An index fund does not deliberately buy more of a company because the company has become expensive. Yet market-cap weighting has that mechanical result when a stock rises faster than the rest of the market: Its weight increases, and new dollars following the index give it a larger place in the portfolio. Wein calls this an inherent momentum effect, referring to the tendency for an investment that has risen to become a bigger holding.
Over time, more and more people are indexed to the S&P 500. I think that it ends up becoming an inherent momentum bet. You’re putting more and more into the larger and larger names, and it kind of feeds on itself.
Wein’s observation is counterintuitive because index funds are commonly associated with broad diversification. And while they do offer ownership across many companies, they are not equal-weight investments. An equal-weight approach assigns similar portfolio weights to each stock, while a market-cap-weighted approach gives the biggest companies the greatest influence. The two approaches can produce very different results when leadership in the market is narrowly concentrated.
For long-term, buy-and-hold investors, the useful response is usually a portfolio review rather than an abrupt sale of every mega-cap holding. Look at the actual weights in an S&P 500 fund, compare them with other stocks and funds already owned, and decide whether the combined exposure matches the investor’s time horizon and tolerance for volatility. Fresh capital can be directed toward a less-concentrated segment if that is the intended portfolio mix.
Related: Ross Gerber’s defensive plan for inflationary markets
Time horizon is key here. Wein said investors seeking large-cap technology exposure with less than a year to invest should be careful about entering solely because of the excitement around those stocks.
He said a horizon well beyond a year made more sense for that exposure, while he viewed mid-caps as a place where “a lot less has to go right.” That, of course, is his assessment, not a forecast that mid-caps will rise over any particular period.
How Hennessy Funds screens for improving mid-cap stocks
Wein’s portfolio is not simply a low-valuation basket. The Hennessy Cornerstone Growth Fund uses a rules-based process that evaluates valuation criteria, earnings improvement, and stock price momentum. He said the process produces a portfolio of 50 names and generally focuses on companies with market capitalizations above $175 million, although the fund is technically an all-cap fund.
The emphasis on earnings improvement is more flexible than a screen that demands fast earnings growth. A company can qualify if its losses are shrinking from one year to the next, according to Wein.
That is called a turnaround: a business moving toward better operating results after a weaker period. The process then requires price behavior that supports the idea that investors are recognizing the improvement.
We’re really looking at improvement. So it’s not even growth. I think that’s important. There could be a name that has lost money and then loses less money the following year.
Wein’s turnaround test helps explain why a low stock price or a low valuation alone is insufficient. A stock can be cheap because a company’s prospects are deteriorating. Conversely, a business with earnings that are stabilizing or improving may deserve further research, but price momentum is the market-based confirmation that Wein wants before the stock enters the portfolio.
Neither measure guarantees a recovery, but these signals can be a place to start.
Investors using a similar idea on their own should avoid treating a single ratio as a buy signal. Start by asking whether earnings are improving, whether the balance sheet can support the business through a setback, and whether the valuation leaves room for disappointment. Then decide how much of a portfolio belongs in a turnaround candidate.
The answer should reflect the investor’s own objectives, not a fund manager’s model.
Why artificial intelligence infrastructure reaches beyond chip stocks
Wein’s largest sector emphasis in the Hennessy Cornerstone Growth Fund was industrials, which he said accounted for almost a quarter of the portfolio at the time of the interview. He tied the allocation to onshoring (moving production or supply-chain activity closer to the domestic market), infrastructure construction, and the buildout of artificial intelligence data centers.
His investment case does not depend on selecting the eventual artificial intelligence software, chip, or large-language-model winner. It focuses on the physical work around the buildout.
Tutor Perini, for example, is an infrastructure company involved in projects including mass transit, bridges, tunnels, hospitals, and shopping malls, according to Wein. He said it met the fund’s valuation, earnings growth, and stock price momentum screens.
Centuri Holdings illustrates another part of the theme. Wein described the company as a provider of utility infrastructure services, including retrofits related to natural-gas transmission. His thesis is that data centers need power and that utility systems may need work to meet that demand. He said Tutor Perini and Centuri Holdings had substantial backlogs, or contracted work still to be completed, that could extend for years.
Those themes do not protect a stock from volatility. Wein said Tutor Perini was up almost 30% year-to-date at the time of the interview and argued that its multiyear projects made the opportunity strategic rather than tactical.
He said Centuri Holdings, on the other hand, was down more than 20% year to date and attributed some of its weakness to energy market volatility.
The different directions underscore why an attractive industry theme and a successful investment are separate questions.
Outside industrials, Wein mentioned equipment-oriented technology, including Diebold Nixdorf, rather than software and semiconductor companies. He also said the fund had meaningful energy exposure across refining, upstream, and downstream businesses.
Upstream energy companies produce oil and gas; downstream companies refine, process, or distribute those products.
Note: These are current portfolio views described in the interview, not individualized recommendations.
Why earnings matter more to Wein than small Federal Reserve moves
Wein’s broader market thesis begins with corporate results. He said second-quarter S&P 500 revenue growth was more than 15% in an economy growing at low single-digit rates, and he viewed that contrast as evidence that investors had shifted some attention away from Federal Reserve policy toward earnings. He also said artificial intelligence investment and infrastructure spending supported the growth story.
His point was not that interest rates are irrelevant. He said a 10-year Treasury yield around 5% did not, in his view, undo the growth case, and that a move to about 5.5% would still not necessarily do so.
He was much less certain above that level. Yields are the annual return investors receive from bonds, expressed as a percentage of the bond’s price, and higher yields can make bonds more competitive with stocks.
Related: Kevin Mahn sees S&P 500 pullbacks as chances to stay invested
Hennessey’s funds do not alter their processes in response to every rate change, Wein said. He argued that a 25-basis-point Federal Reserve move should not drive major portfolio decisions. A basis point is one-hundredth of a percentage point, so 25 basis points equals 0.25 percentage points.
Investors with short-term cash needs or unusually rate-sensitive holdings may reasonably reach a different conclusion.
How oil prices could challenge an earnings-driven market case
The risk Wein emphasized was a sustained rise in oil prices, particularly one connected to events in the Middle East. He said higher energy costs can filter through shipping, component prices, household confidence, and the broader economy. That mechanism matters because stronger earnings can support stock valuations only as long as businesses and consumers can absorb the costs.
He remained bullish, forecasting that the market could add another 5% to 10% by year-end from the point of the interview. He based that view on equal-weight valuations and continued earnings progress.
His forecast is a bare outlook rather than evidence that investors should expect that result, and it should be weighed against his stated oil risk and the possibility that earnings or interest-rate conditions disappoint.
The takeaway for S&P 500 investors considering mid-caps
- The first decision is not whether the S&P 500 is broadly “too expensive.” It is whether an investor’s portfolio has become more concentrated in mega-cap stocks than they intended. A long-term, buy-and-hold investor can answer that by reviewing fund overlap, the weights of the largest holdings, and the amount of money needed in the near term before changing an allocation.
- The second decision is whether a mid-cap allocation fits the portfolio’s purpose. Wein’s case rests on lower relative valuations, diversification away from mega-caps, and a process that seeks improving businesses with market confirmation.
- Investors who choose to explore the area can use those same questions as a research checklist, while recognizing that mid-caps, turnarounds, infrastructure companies, and energy-linked businesses all carry their own risks.
- Finally, investors should separate a market theme from a buying decision. Artificial intelligence data-center construction, onshoring, and infrastructure spending may create demand for particular companies, but the price paid, earnings trajectory, and role in a diversified portfolio still determine whether a stock belongs in an individual investor’s plan.
Wein’s central argument is that index-level valuation can conceal important differences underneath the surface. For investors, the practical value lies less in predicting the next S&P 500 move than in knowing how much mega-cap concentration they hold, why they hold it, and whether a measured mid-cap allocation would improve their existing portfolio.
Related: Peter Schiff’s case for more gold & foreign stocks (& less U.S. tech) in your portfolio