
Taiwan Semiconductor Manufacturing Co. (TSM) counts Apple (AAPL) and Nvidia (NVDA) among its top customers for 2nm chips, according to Seeking Alpha. So when TSMC adds capacity, investors usually look to those customers to see who benefits. Wells Fargo is looking somewhere else.
Analyst Joe Quatrochi weighed in on a possible 2nm expansion at TSMC in a note to clients on Tuesday, September 29, 2026. He called it a “potentially incremental positive opportunity for semi cap companies,” Seeking Alpha reported.
Semi cap is Wall Street shorthand for firms that build chipmaking tools, such as Applied Materials (AMAT), Lam Research (LRCX), KLA (KLAC) and ASML Holding (ASML). They rarely get the attention TSMC’s customers do, but they are usually the first to get paid.
Nothing is official yet. Even so, Quatrochi’s logic holds up, and it starts with timing.
Chip equipment makers get paid before TSMC does
A chip factory earns nothing until its machines are running. That lag sits at the heart of Wells Fargo’s call.
TSMC’s 2nm chips made up just 3% of its wafer revenue in the second quarter, according to the company’s July earnings release. The node Wall Street watches most has barely made it onto TSMC’s income statement.
Related: TSMC’s rivals are losing ground, and the gap is growing
That is about to change. CFO Wendell Huang said in the same release that a steep 2nm ramp will support third-quarter business. A steep ramp needs tools to be installed months before chips ship, so equipment makers usually see the orders first.
TSMC’s board approved about $29.4 billion in capital spending on Tuesday, August 11, 2026, mainly to install and upgrade advanced capacity, a company filing shows. Much of that money buys machines.
The customer list widens the ripple. Beyond Apple and Nvidia, TSMC’s 2nm customers include Advanced Micro Devices (AMD), Qualcomm (QCOM), Google parent Alphabet (GOOGL), Broadcom (AVGO), Marvell Technology (MRVL), Amazon (AMZN) and OpenAI, Seeking Alpha reported.
Equipment makers don’t have to guess which company will win the AI race. Their payday depends on how much TSMC builds and where.
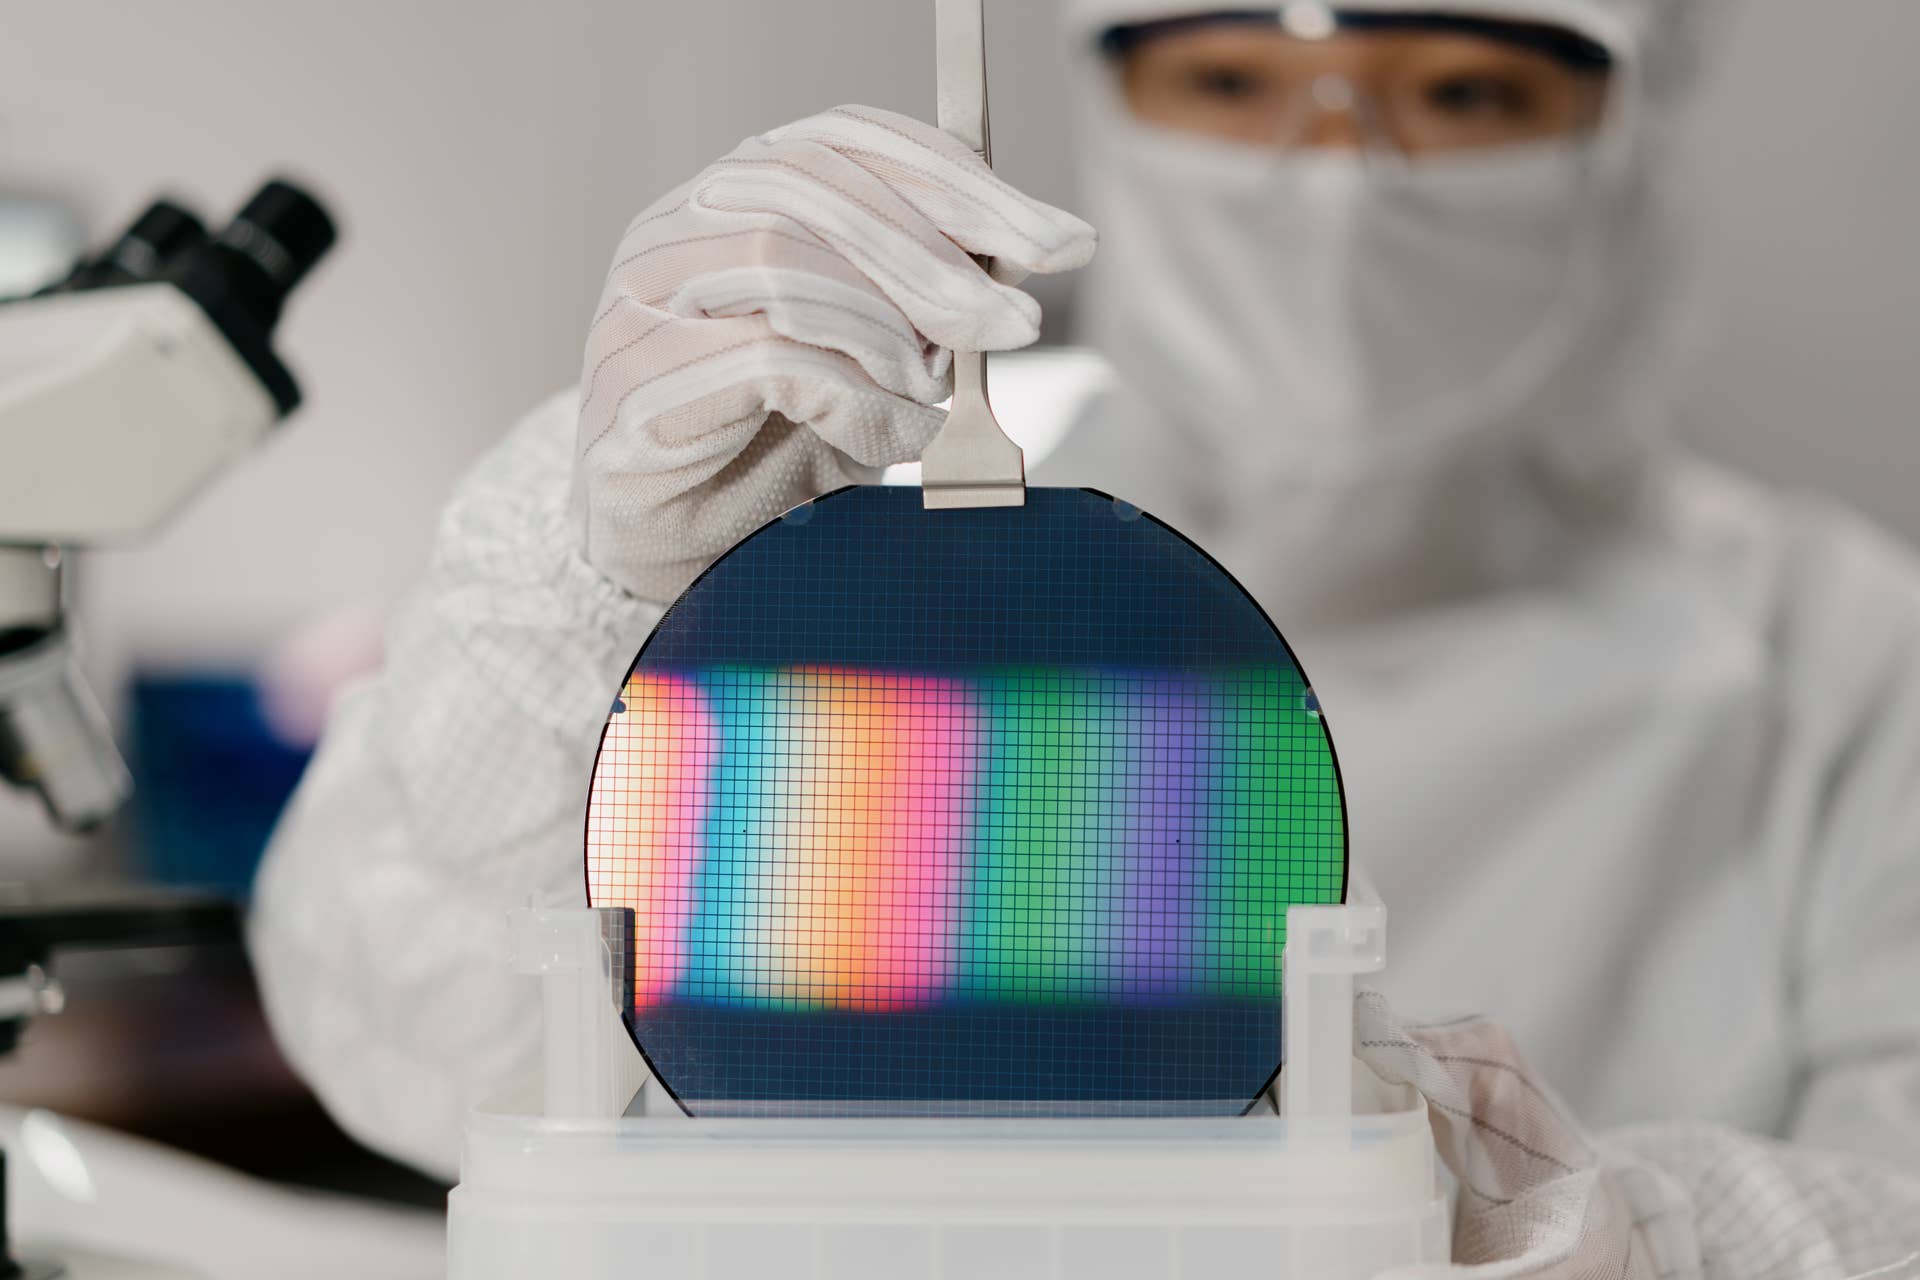 TSMC’s 2nm chips made up just 3% of its wafer revenue in the second quarter, but Wells Fargo says a possible expansion could lift chip equipment makers.
A second US campus would mean buying every tool again
Quatrochi also suggested a likely address. He said Texas’s Silicon Prairie would be a logical home for a second campus. Texas Instruments, Samsung Electronics, Coherent and Terafab already have fab operations there, he noted.
A new campus would not move capacity out of Arizona or Taiwan. It would duplicate it, which means buying a fresh set of machines that print, etch and inspect circuits for each fab.
Arizona shows how fast these plans grow. In December 2022, a week after ChatGPT launched, TSMC put the cost of two Arizona fabs at about $40 billion, according to a company filing.
By July 2026, TSMC’s Arizona pledge had reached $265 billion, CNBC reported.
Huang told CNBC the additional $100 billion will fund wafer fabs and advanced packaging plants. A Texas campus would add to that unfinished buildout. For toolmakers, that means one multiyear order book layered on another.
Still, key pieces are missing. Wells Fargo is waiting on timing, size and node details, and TSMC did not immediately respond to Seeking Alpha. According to Stock Analysis, TSMC reports third-quarter results on Thursday, October 15, 2026. That call gives management its next chance to address US plans.
Analysts still see upside in TSMC stock
TSMC is the world’s leading dedicated chip foundry, according to its own filings, meaning it builds chips that other companies design. Its stock is one bet on nearly every major AI chip program.
TSMC’s market value has grown from about $379 billion at the end of 2022 to roughly $2 trillion, according to Stock Analysis. That is more than a fivefold gain since the AI boom began.
The stock trades at about 29 times trailing earnings but roughly 20 times forward earnings, per Stock Analysis. That gap shows analysts expect profits to keep climbing quickly.
Shares have traded between $266.82 and $479 over the past 52 weeks, according to Stock Analysis. The 21 analysts it tracks give TSMC a consensus Strong Buy rating, with an average price target of $552.26. The site pegs that at about 21% upside, even after the stock’s long run.
More TSMC:
- An AI chip machine so pricey, three rivals had to say yes
- TSMC hikes 2026 guidance as AI demand outpaces capacity
- TSMC’s rivals are losing ground, and the gap is growing
The AI trade is becoming a construction story
For most of the AI boom, investors asked who designs the best chips. TSMC’s buildout asks who gets paid to build the capacity.
TSMC lifted its 2026 capital spending plan to as much as $64 billion, CNBC reported.
A Texas campus would stretch that cycle further. That makes toolmakers’ order books an early read on how big TSMC’s American bet becomes. The brands on the box get the headlines, but the machine makers usually see the future first.
Related: Why is Taiwan hiding the backers of its $20B US pledge?
